Key takeaways
No prop firm is a defensible universal winner for largest drawdown because usable loss buffer depends on asset class, program, account phase, daily loss limit, breach threshold, reset timing, withdrawals, and whether drawdown is static, trailing, balance-based, equity-based, intraday, or end-of-day.
Read the full summary
No prop firm is a defensible universal winner for largest drawdown because usable loss buffer depends on asset class, program, account phase, daily loss limit, breach threshold, reset timing, withdrawals, and whether drawdown is static, trailing, balance-based, equity-based, intraday, or end-of-day. A hypothetical $100,000 account with 10% static drawdown keeps a $90,000 threshold even after reaching $105,000, leaving a $15,000 gap, while a $10,000 trailing allowance could raise the threshold from $90,000 to $95,000 after the same gain. Likewise, 12% maximum drawdown with a 4% daily limit makes the daily rule the immediate constraint, and a $95,000 balance with a $2,000 unrealized loss produces $93,000 equity under an equity-based check. Forex and CFD percentage limits should be compared separately from futures fixed-dollar allowances, nominal tiers, contract limits, scaling conditions, and trailing thresholds. Audacity Capital, FXIFY, affiliate comparisons, and Reddit discussions can support discovery but not current rule verification. Check first-party documents before purchase, each new phase, payouts, and scaling, save dated evidence, and separately verify instruments, position limits, consistency rules, trading-day requirements, restricted periods, inactivity rules, payout conditions, prohibited strategies, fees, and platforms.
How we researched this article
BestProps used document-based research from primary firm sources, checked September 12, 2026. The complete source list, scope, limitations, and commercial-state record appear near the end of this article.
Finding the prop firm with the largest drawdown is not as simple as comparing percentages. A program advertising a 12% maximum drawdown may offer less practical room than one advertising 10%, depending on whether the limit is static, trailing, balance-based, equity-based, intraday, or calculated at the end of the day.
Daily loss limits, account phases, profit withdrawals, and open-position equity can further reduce the usable buffer. Rules also change frequently, so a universal winner cannot be established without checking current first-party documentation for the exact program being considered.
Quick answer: The largest headline percentage does not necessarily provide the largest usable drawdown. Compare the breach threshold, calculation method, daily limit, reset timing, and evaluation-versus-funded rules before ranking programs.
Why No Prop Firm Has the Largest Drawdown for Everyone
Search results for high-drawdown prop firms contain conflicting figures and different definitions. Some comparison pages focus on forex and CFD evaluations, while others cover futures programs. Some use the maximum loss published for an evaluation; others appear to reference funded-stage rules or a particular account option.
Commercial incentives also matter. Several prominent articles are published by prop firms or affiliate-supported comparison sites. For example, Audacity Capital discusses high-drawdown programs, while FXIFY focuses on static drawdown. These pages may be useful starting points, but promotional rankings should not be treated as independent verification.
Community discussions, including a Reddit discussion about daily and maximum loss limits, show that traders care about both limits. However, Reddit comments are qualitative audience evidence, not confirmation of current firm rules.
How to Compare the Largest Usable Drawdown
A fair comparison starts by normalizing each program. Record the following information from the firm’s current rule page or agreement:
| Field to record | What to capture |
|---|---|
| Asset class: | Separate forex and CFD programs from futures programs. |
| Program and account size: | Rules can differ between account options offered by the same firm. |
| Account phase: | Record evaluation and funded-stage limits separately. |
| Maximum drawdown: | Note both the percentage and monetary threshold. |
| Daily loss limit: | Determine whether this can cause a breach before maximum drawdown is reached. |
| Drawdown method: | Classify it as static, trailing, balance-based, equity-based, or a combination. |
| Calculation timing: | Check whether limits are monitored intraday or updated at the end of the trading day. |
| Reference point: | Identify whether the threshold follows starting balance, closed balance, peak balance, or peak equity. |
| Withdrawal treatment: | Determine whether payouts alter the threshold or remaining buffer. |
| Source and date: | Save the official URL and the date on which the rule was verified. |
Without those fields, ranking one firm above another can create a false comparison. A list that shows only percentages leaves out the rules most likely to determine whether an account breaches.
Static and Trailing Drawdown at Prop Firms
How Static Drawdown Works
A static drawdown threshold generally stays anchored to a defined starting value. Consider a hypothetical $100,000 account with a 10% static maximum loss limit based on starting balance. Its breach threshold would remain at $90,000, assuming no separate rule modifies it.
As checked August 25, 2026, FTMO’s official Trading Objectives describe the 2-Step Maximum Loss Limit as static and set the Maximum Loss Amount at 10% of Initial Simulated Capital. The same source lists a separate 5% Maximum Daily Loss Amount, so the daily rule can constrain a 2-Step account before the overall maximum-loss threshold. This bounded example does not establish that FTMO has the largest usable drawdown or describe another provider or FTMO’s 1-Step calculation.
If the account rises to $105,000, the threshold remains $90,000 under this simplified example. The trader therefore has a $15,000 gap between current balance and the maximum-loss threshold. This is why traders often view a genuinely static structure as easier to model.
The word static is not enough on its own. Traders should still verify whether open equity counts, whether a daily limit applies, and whether the funded account uses the same calculation as the evaluation.
How Trailing Drawdown Works
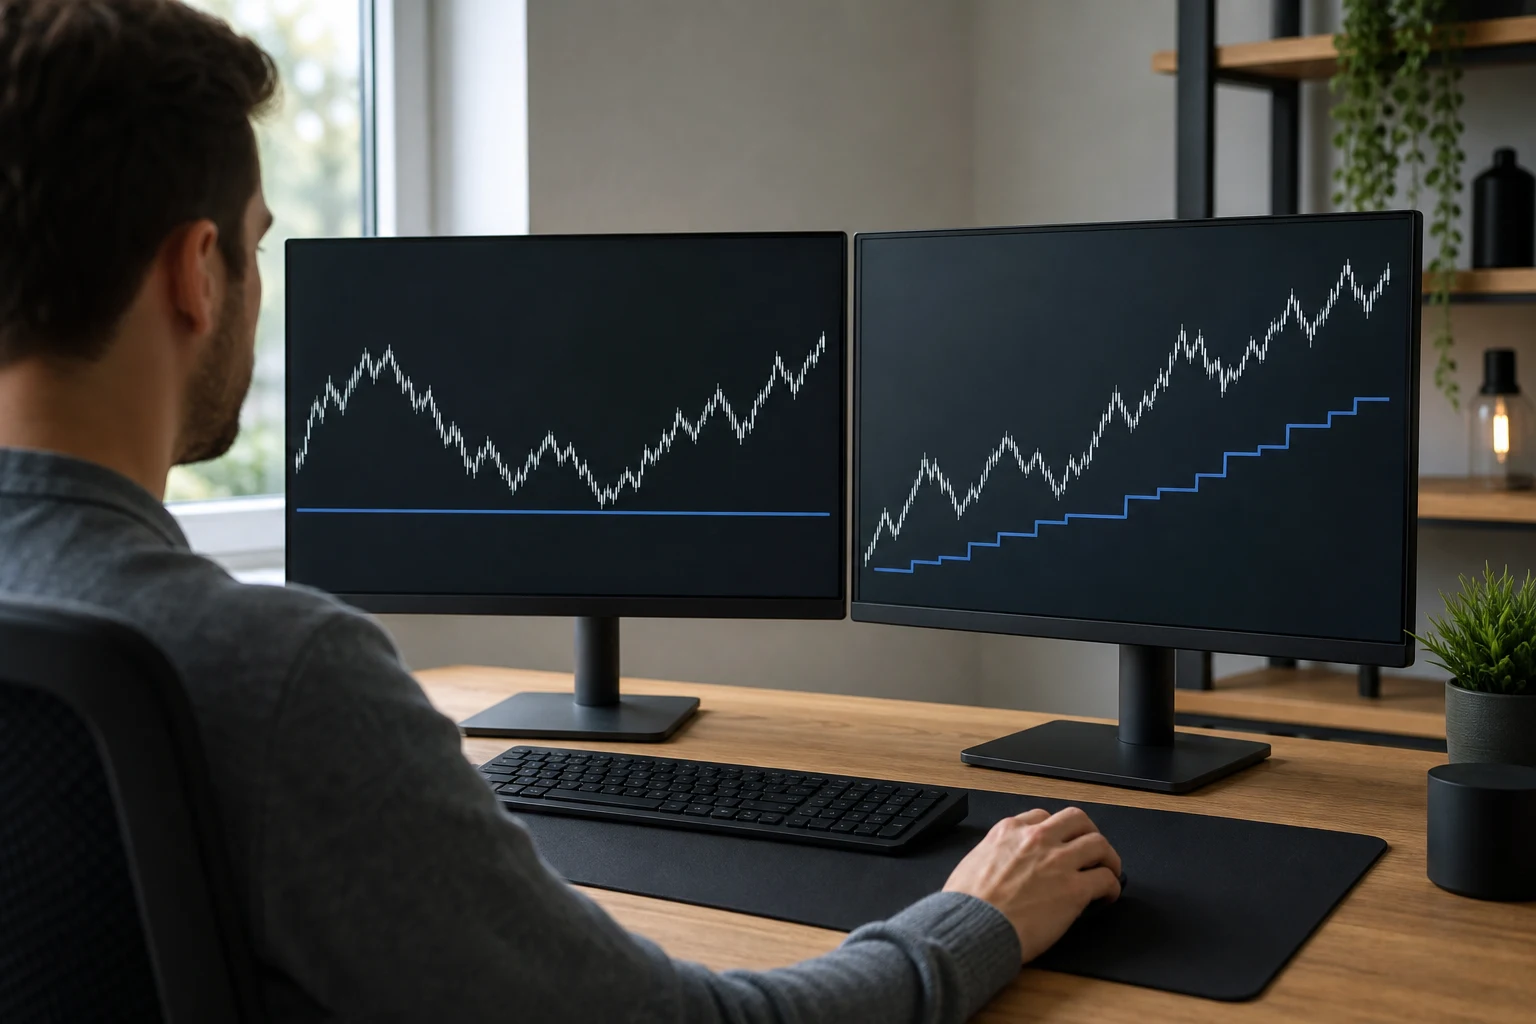
A trailing drawdown follows a specified high-water mark. In a simplified $100,000 account with a $10,000 trailing allowance, the initial threshold would be $90,000. If the tracked balance or equity reaches $105,000, the threshold could rise to $95,000.
That change reduces how much of the earlier gain can be surrendered. The practical result also depends on whether the threshold trails closed balance or unrealized equity, whether it updates intraday or at the end of the day, and whether it eventually stops moving.
Two programs can therefore publish the same 10% figure but provide materially different trading room. A static 10% allowance and an intraday equity-trailing 10% allowance should not be placed in the same ranking column without explanation.
How Prop Firms Calculate the Real Loss Buffer
A balance-based rule usually references realized account balance. An equity-based rule can include unrealized profit and loss from open positions. That distinction is particularly important for strategies that hold positions through volatile periods or manage several correlated trades.
Suppose a hypothetical account has a $95,000 balance and an open position showing a $2,000 unrealized loss. Its equity is $93,000. A balance-based check may reference $95,000 at that moment, while an equity-based check may reference $93,000. The applicable documentation determines whether either figure constitutes a breach.
Labels vary between providers, so traders should look for the actual formula rather than relying on category names used by comparison sites.
Why Daily Loss Limits Reduce the Drawdown Buffer
A generous maximum drawdown does not eliminate a restrictive daily limit. Imagine a hypothetical program offering 12% maximum drawdown but only 4% daily loss. A trader cannot necessarily use the full 12% buffer during a difficult session because the daily rule can end the account first.
Daily loss calculations may include closed losses, open losses, commissions, or other trading costs. The reset can also depend on a specified time zone. Positions held across the reset may create additional complexity if equity is measured before and after that point.
When comparing prop firms with high drawdown, calculate two separate distances:
- The distance from current equity to the overall breach threshold.
- The distance from current equity to the daily breach threshold.
The smaller distance is usually the immediate constraint. Traders should monitor both rather than treating maximum drawdown as the complete risk budget.
Compare Drawdown Across Forex and Futures Prop Firms
Forex and CFD evaluations often present risk limits as percentages of an advertised account size. Futures programs may instead express the loss allowance as a fixed monetary amount associated with a nominal account tier. These structures are not directly comparable without converting them into both dollars and percentages and then examining how the threshold moves.
Even that conversion can be misleading. A nominal futures account size may not represent deployable capital in the same way a trader initially assumes. Contract limits, scaling conditions, and trailing thresholds can shape the effective risk allowance. Keep forex and CFD programs in one comparison group and futures programs in another.
How to Shortlist a Prop Firm by Drawdown
Instead of selecting the largest number on a ranking page, use this process:
- Define the strategy requirement. Estimate normal stop distance, typical simultaneous exposure, holding period, and expected open-equity fluctuation without assuming future profitability.
- Choose the preferred method. Decide whether a static threshold is essential or whether a clearly defined trailing rule is manageable.
- Check the daily constraint. Confirm that ordinary planned risk would remain within the daily limit, including open positions and costs where applicable.
- Separate each phase. Review evaluation and funded rules independently rather than assuming they match.
- Read first-party documents. Use comparison pages for discovery, then confirm every material rule with the provider.
- Save evidence. Keep a dated copy or screenshot of the applicable rules and recheck them before purchasing an evaluation.
- Test the formula. Work through scenarios involving profits, losses, open positions, day resets, and withdrawals.
Compare Prop Firm Rules Beyond Drawdown
The highest drawdown is only one part of program suitability. Traders should also investigate permitted instruments, position and contract limits, consistency requirements, minimum or maximum trading days, restricted trading periods, inactivity rules, payout conditions, and prohibited strategy language.
Do not infer these terms from a drawdown comparison article. They are firm-specific, may differ by program, and require current verification. Fees and platform availability are similarly time-sensitive.
Prop Firm Drawdown Questions
Is a Higher Maximum Drawdown Always Better?
What Is the Easiest Drawdown Type to Track?
Can Evaluation and Funded Drawdown Rules Differ?
How Often Should Prop Firm Rules Be Rechecked?
Choosing a Prop Firm With the Best Drawdown Buffer
There is no defensible universal answer to which prop firm has the largest drawdown unless the comparison specifies asset class, program, account phase, daily limit, calculation method, and verification date. Current search results contain promotional superlatives and conflicting figures, so headline percentages alone do not support naming a winner.
The better objective is to find the largest usable loss buffer compatible with a defined risk plan. Normalize the rules, separate static from trailing structures, calculate daily and overall thresholds, and verify every firm-specific detail at the source. Drawdown room can reduce the chance of an accidental rule breach, but it does not promise trading success or remove market risk.